Cash Is Still King in Morocco, but Fintech Is Coming for the Crown
Morocco runs on cash, yet mobile wallets, instant transfers, and payment startups keep growing. Why changing payment habits is slow — and why it is happening anyway.
The cash paradox
Morocco has modern banks, near-universal mobile coverage, and millions of bank cards — and an economy that still prefers banknotes. Cash feels free, instant, and private; cards and wallets must beat that feeling, not just match it, which is why fintech progress here is measured in years, not quarters.
What is already working
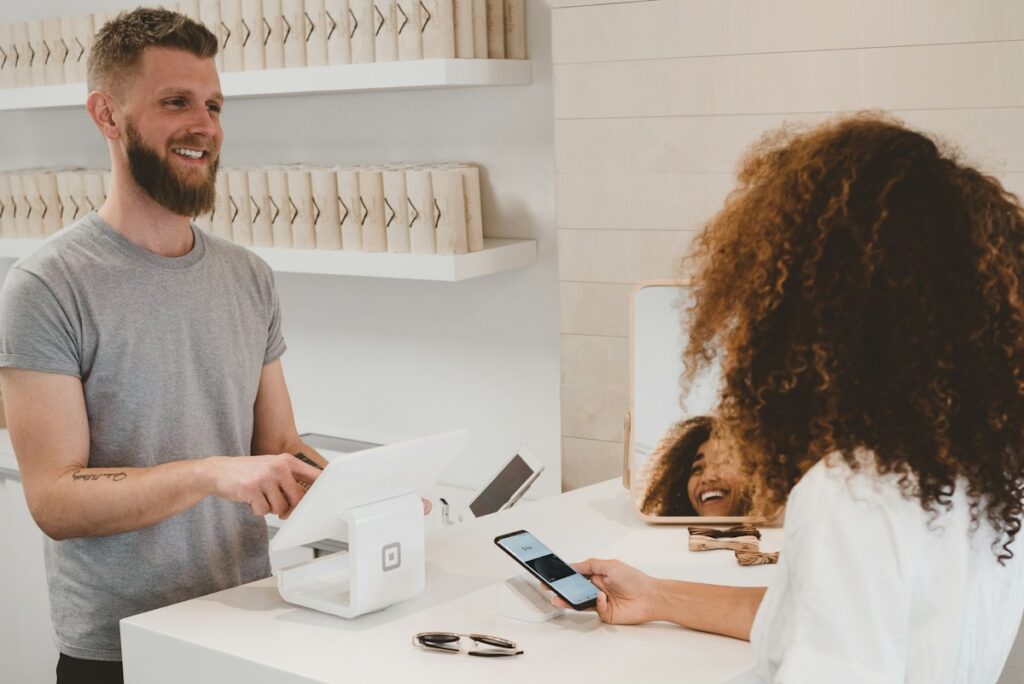
Mobile wallets from banks and telecom-linked providers have grown steadily, helped by low fees and agent networks that reach small shops. Instant interbank transfers have made phone-to-phone payments normal for a growing slice of urban users, and e-commerce — built around cash on delivery — is slowly training buyers to pay in advance.
The merchant bottleneck
Payments change when shops change. Small merchants weigh terminal costs, settlement delays, and tax visibility against cash’s simplicity. The fintechs making progress in Morocco tend to sell the merchant something bigger than payments: customer reach, credit history, or tools to run the shop.
Regulation’s role
Bank Al-Maghrib has spent years building the rails — interoperability, agent banking, and consumer protection — and pushing financial inclusion as national policy. The central bank’s steady hand is a big reason Morocco’s fintech growth, while slower than hype elsewhere, rests on real infrastructure.
What to watch
Three signals will tell if the crown is really contested: wallet payments accepted in souks and taxis, not just apps; instant transfers becoming the default among young users; and startups building credit and savings products on top of payment data. Cash will not vanish — but its monopoly is ending.
Photo: Unsplash. TrendWire covers Moroccan and global tech in plain language — follow the Tech, Startups, Software, Cybersecurity and AI sections for more.